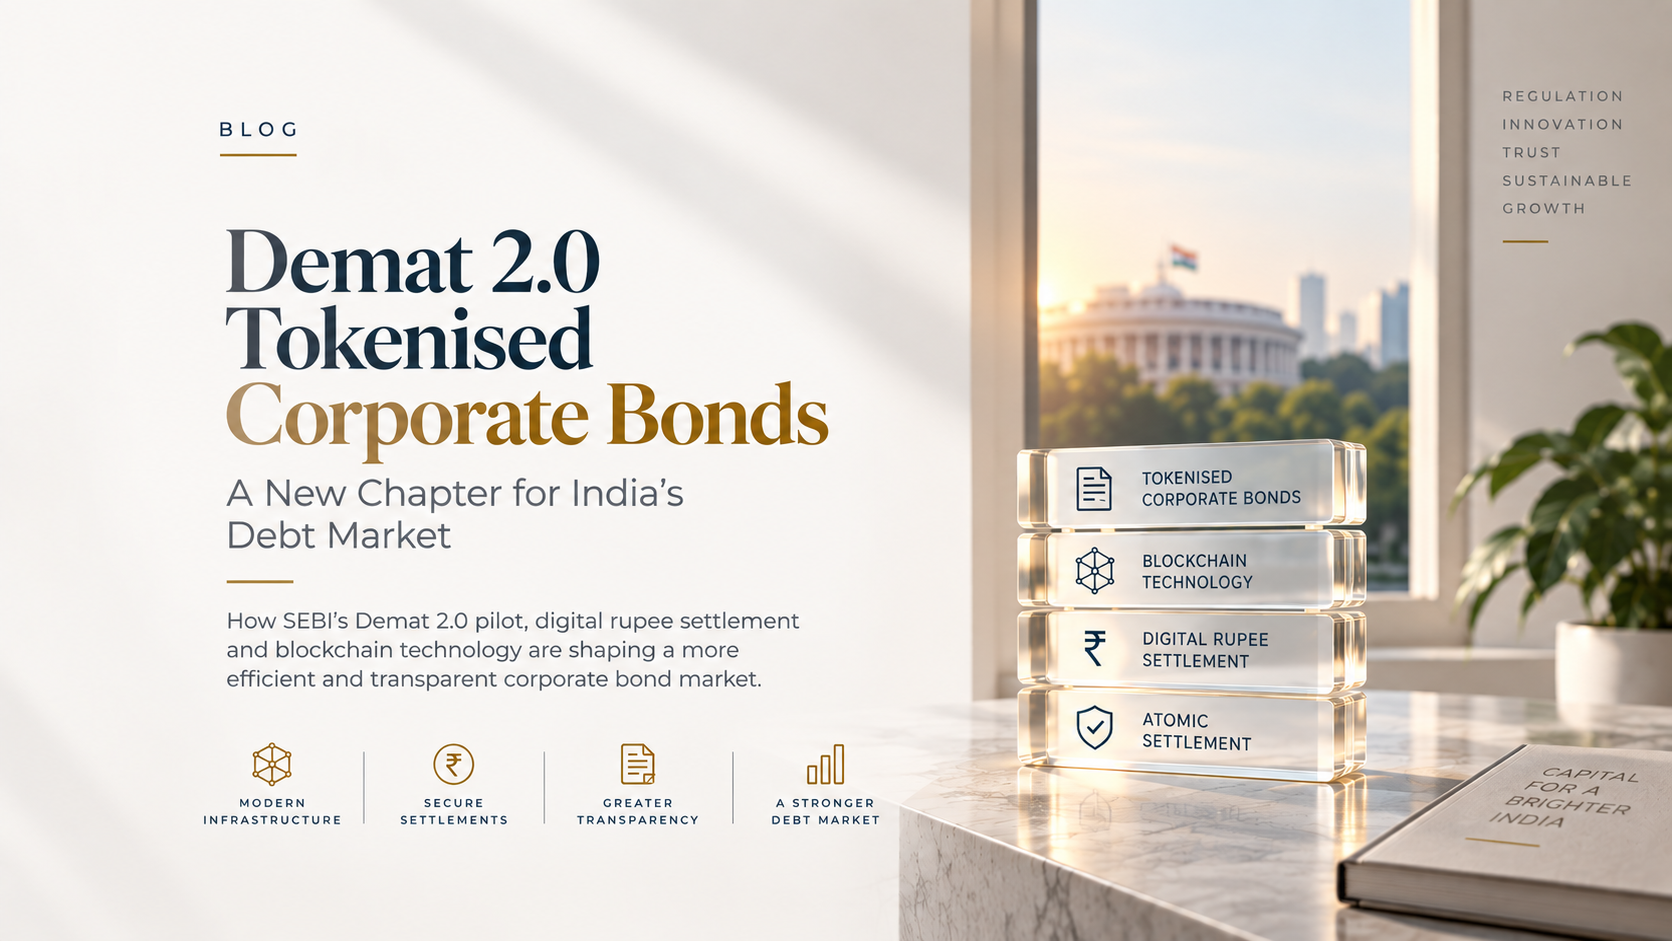
India’s corporate bond market is entering a new phase of technological development with the launch of Demat 2.0 tokenised corporate bonds. The Securities and Exchange Board of India (SEBI), in collaboration with the Reserve Bank of India (RBI), has launched a pilot that combines distributed ledger technology with the RBI’s wholesale central bank digital currency (CBDC).
The initiative was announced at the Global Fintech Fest in Mumbai on September 10, 2026. According to SEBI, the pilot is designed to modernise the issuance, holding, trading and settlement of corporate bonds while retaining the existing legal and regulatory framework applicable to these securities.
For participants in India’s debt and NCD market, the development is relevant because it explores how securities-market infrastructure can evolve through technology without changing the underlying legal character of the financial instrument.
What Is Demat 2.0?
Demat 2.0 is a pilot initiative that uses distributed ledger technology to represent corporate bonds as digital tokens within a regulated securities-market environment. The initiative does not create a new category of unregulated digital assets. Instead, it explores the use of technology for processing an existing financial instrument.
Under the pilot, corporate bonds are issued as digital tokens on a distributed ledger maintained within the regulated market infrastructure. The securities infrastructure is connected with the RBI’s wholesale digital rupee through the Unified Market Interface.
This creates an architecture in which the securities leg and the cash leg of a transaction can be connected more closely. The objective is to examine whether this can improve the efficiency of issuance and settlement while maintaining the regulatory safeguards that apply to corporate bonds.
What Are Demat 2.0 Tokenised Corporate Bonds?
Demat 2.0 tokenised corporate bonds are corporate debt securities represented digitally using distributed ledger technology under the pilot framework.
The important point for investors is that tokenisation does not change the fundamental nature of the underlying bond. The issuer’s obligations remain applicable, and the rights attached to the security continue to be governed by the relevant legal and regulatory framework.
In other words, the innovation is primarily in the infrastructure used to represent, transfer and service the security. It should not be interpreted as a change in the fundamental risk or return characteristics of the underlying corporate bond.
This distinction is particularly important for communication around NCDs and other debt securities. Technology can change how a security is processed, but it does not by itself eliminate credit risk, liquidity risk, interest-rate risk or other risks associated with debt investments.
How Does Demat 2.0 Work?
The Demat 2.0 framework connects tokenised corporate bonds with the RBI’s wholesale digital rupee. The securities are represented through distributed ledger technology, while the corresponding payment can be made through the wholesale CBDC infrastructure.
The integration is designed to facilitate what is known as atomic settlement. Under this model, the transfer of the security and the corresponding payment can take place together, subject to the applicable transaction conditions.
In a conventional settlement process, securities and payments may move through separate systems and processes. Connecting the two legs of a transaction is intended to reduce the settlement exposure that can arise when delivery and payment do not occur simultaneously.
The pilot therefore provides an opportunity to assess whether distributed ledger technology and central bank digital currency can work together within India’s established securities-market framework.
What Is Atomic Settlement?
Atomic settlement is one of the key concepts behind Demat 2.0 tokenised corporate bonds.
In simple terms, atomic settlement refers to a transaction structure in which the transfer of the security and the corresponding payment occur simultaneously. This can help reduce the risk associated with one side of a transaction being completed without the other side being completed.
For the corporate bond market, such a structure could have operational relevance because settlement involves the movement of both securities and funds.
However, the introduction of atomic settlement should not be interpreted as eliminating all investment or market risks. It primarily addresses the mechanics of settlement between the relevant parties.
Role of the RBI’s Wholesale Digital Rupee
The RBI’s wholesale digital rupee, or e₹-W, is an important component of the Demat 2.0 pilot.
Unlike a retail CBDC intended for general consumer payments, wholesale CBDC is designed for financial-market and institutional use cases. Under Demat 2.0, the wholesale digital rupee provides the payment component for transactions involving tokenised corporate bonds.
The integration of tokenised securities with central bank digital currency is significant because it brings the securities and payment infrastructure closer together.
For the Indian financial system, this represents an experiment in applying digital technology to regulated capital-market infrastructure rather than creating a separate market outside the existing regulatory framework.
Three Issuers Have Participated in the Initial Pilot
The initial implementation of Demat 2.0 has already recorded three corporate bond issuances with a combined value of ₹1,025 crore.
REC Ltd became the first issuer under the pilot on September 7, 2026, raising ₹500 crore from 18 investors. Larsen & Toubro Ltd followed on September 9 with a ₹500 crore issue subscribed by four investors. IIFL Finance also issued ₹25 crore of tokenised bonds on September 9 to a single investor.
These transactions represent the initial live implementation of the pilot and provide an opportunity for market participants and regulators to evaluate the technology under actual transaction conditions.
The initial issuances should, however, be understood in the context of a pilot. They do not by themselves establish the eventual size, liquidity or adoption of tokenised corporate bonds in India.
Does Tokenisation Change Investor Rights?
According to SEBI’s description of the pilot, tokenisation does not alter the existing legal rights associated with the corporate bonds.
The securities continue to be subject to the applicable regulatory requirements. Issuer obligations, including repayment obligations, remain applicable. Requirements relating to credit ratings, debenture trustees, listing and disclosures also continue to be relevant.
This approach is important because it separates technological innovation from investor protection.
The use of distributed ledger technology does not mean that the normal regulatory framework applicable to corporate bonds has been replaced. Instead, the pilot examines whether the technology supporting the market can be improved while maintaining that framework.
What Does Demat 2.0 Mean for the NCD Market?
For companies and institutions operating in India’s NCD and corporate debt ecosystem, Demat 2.0 represents an important development in securities-market infrastructure.
NCDs are debt instruments through which issuers raise funds from investors. Their investment characteristics depend on factors such as the issuer, credit profile, security structure, tenure, interest rate, repayment terms and applicable offer documents.
Demat 2.0 focuses on how such securities can potentially be issued, recorded, settled and serviced using distributed ledger technology.
Therefore, the development is relevant to the broader NCD ecosystem from an infrastructure perspective rather than because tokenisation automatically changes the investment characteristics of NCDs.
Potential Improvements in Issuance Processes
One area being examined through the pilot is the time required for settlement of primary issuances.
SEBI has stated that the pilot can enable issuers to receive subscription funds on the same day as bidding, compared with processes that may otherwise take two to three days.
A more integrated settlement process may also reduce some reconciliation and validation activities between different participants in the transaction.
These are operational objectives of the pilot. Their actual impact will need to be evaluated as the system is used more extensively and across a broader range of transactions.
Automation of Interest Payments and Redemption
Corporate bonds require servicing throughout their tenure. Depending on the terms of the instrument, this can include periodic interest payments and repayment of principal at maturity.
Demat 2.0 explores the use of smart contracts to automate certain post-issuance processes. Under the proposed structure, predefined instructions can be used to facilitate eligible interest payments and redemption-related processes.
This could potentially reduce manual intervention and reconciliation requirements.
For issuers and intermediaries, automation may therefore become an important area of operational efficiency. At the same time, appropriate controls, validation mechanisms and regulatory oversight remain essential when automating financial transactions.
What Could This Mean for Investors?
For investors, the potential relevance of Demat 2.0 lies primarily in the transaction and servicing infrastructure.
If tokenised corporate bonds are eventually enabled for secondary-market trading, the integration of the security and payment legs could potentially facilitate faster settlement.
However, faster settlement should not be confused with lower investment risk.
An investor considering an NCD or corporate bond should continue to examine the issuer’s financial position, credit rating where applicable, security or charge structure, tenure, interest payment terms, redemption terms, liquidity considerations and the risk factors contained in the relevant offer documents.
The technological format of a security should not be treated as a substitute for evaluating the underlying investment.
Demat 2.0 and Secondary-Market Trading
The current pilot focuses on primary issuance. However, SEBI has indicated that subsequent phases are expected to explore secondary-market trading of tokenised corporate bonds through existing Request-for-Quote platforms.
This could be an important next stage because primary issuance tests the creation and settlement of a bond, whereas secondary-market trading introduces additional considerations such as price discovery, liquidity, transaction volumes and participation by different categories of market participants.
The integration with existing RFQ infrastructure also indicates that the objective is not necessarily to create an entirely separate market for tokenised securities.
Instead, the broader direction is toward integrating new technology with existing regulated market mechanisms.
Retail Participation Could Be a Later Phase
Retail participation is not the primary focus of the initial Demat 2.0 phase.
SEBI has indicated that the pilot will be implemented progressively, with the initial stage focused on primary issuances. Secondary-market trading is expected to be explored in subsequent phases, with potential retail access being considered at a later stage.
This phased approach provides regulators and market institutions with an opportunity to evaluate the technology, operational processes and participant experience before considering wider adoption.
The eventual structure of retail participation will depend on the outcome of the pilot and subsequent regulatory decisions.
Why Demat 2.0 Is Relevant to India’s Corporate Bond Market
India has been working to develop and deepen its corporate bond market. Digital infrastructure can play a role in making market processes more integrated and efficient.
Demat 2.0 adds another dimension to this development by exploring tokenisation within the regulated securities ecosystem.
The significance of the pilot is not simply that corporate bonds are being placed on a distributed ledger. More importantly, the initiative connects the digital representation of the security with central bank digital currency for settlement.
This combination provides a practical environment in which the potential benefits and limitations of tokenised securities can be evaluated.
Tokenised Bonds Are Not the Same as Cryptocurrencies
The use of the word “tokenised” can sometimes lead to confusion with cryptocurrencies.
The two concepts should not be treated as equivalent.
A tokenised corporate bond under the Demat 2.0 framework represents a regulated financial security. Its issuance, ownership, transfer and servicing take place within the applicable securities-market framework.
The payment component under the pilot is also connected to the RBI’s wholesale digital rupee rather than a privately issued cryptocurrency.
Consequently, Demat 2.0 tokenised corporate bonds should be understood as an application of distributed ledger technology to regulated debt-market infrastructure.
What Risks Should Investors Continue to Consider?
The introduction of tokenisation does not remove the risks associated with corporate debt securities.
Credit risk remains relevant because an issuer’s ability to meet its interest and principal obligations is an important consideration. Liquidity risk can also remain relevant because the ability to sell a security may depend on market conditions and the availability of buyers.
Interest-rate movements can affect the market value of debt securities, particularly when investors seek to sell before maturity. The terms of each NCD or corporate bond can also differ, including with respect to security, seniority, tenure, interest payments and redemption.
Therefore, investors should read the relevant offer documents and risk factors carefully before making any investment decision.
Technology Does Not Mean Guaranteed Returns
For an NCD company, this distinction is particularly important in communicating about developments such as Demat 2.0.
Tokenisation is an infrastructure development. It does not guarantee investment returns, eliminate credit risk or indicate that a particular corporate bond is suitable for every investor.
Any communication relating to debt securities should therefore remain factual and should not create an impression of assured returns, guaranteed repayment or absence of risk.
SEBI’s advertising framework specifically requires communications relating to debt securities to be accurate, fair, clear and complete and prohibits false, misleading, biased or deceptive statements. It also restricts advertisements based on assumptions or projections and requires the prescribed risk warning for debt securities.
What Happens Next for Demat 2.0?
The next stage of the initiative will be important for assessing the practical effectiveness of the technology.
The current phase provides an opportunity to evaluate primary issuance and settlement. Subsequent phases are expected to explore secondary-market trading, followed by the possibility of broader investor participation.
The experience generated through these phases can help regulators determine how tokenised corporate bonds should develop within India’s securities-market framework.
The success of the initiative will therefore depend not only on technological functionality but also on factors such as market participation, operational resilience, cybersecurity, interoperability, investor protection and regulatory compliance.
The Broader Future of Tokenisation in India
The implications of Demat 2.0 may extend beyond corporate bonds if the pilot demonstrates that distributed ledger technology can operate effectively within regulated financial-market infrastructure.
Tokenisation could potentially be examined for other financial instruments and market processes in the future. However, each application would require its own regulatory, operational and risk assessment.
For now, Demat 2.0 should be viewed as a focused pilot for tokenised corporate bonds rather than as a broad transformation of every segment of India’s financial market.
What Demat 2.0 Means for the Future of NCDs
The NCD market is built around a straightforward financial concept: an investor provides funds to an issuer in return for contractual debt obligations, including applicable interest and repayment of principal.
Demat 2.0 does not change this fundamental relationship.
Instead, it explores whether the infrastructure supporting that relationship can become more digital, integrated and automated.
For issuers, intermediaries and investors in India’s debt market, this could eventually result in changes to how securities are issued, settled and serviced. However, those developments will depend on the outcomes of the pilot and subsequent regulatory decisions.
Conclusion
Demat 2.0 tokenised corporate bonds represent an important development in the digitalisation of India’s corporate bond market. SEBI and RBI are testing a framework in which corporate bonds can be represented through distributed ledger technology while payments are settled using the RBI’s wholesale digital rupee.
The initial ₹1,025 crore of issuances by REC, Larsen & Toubro and IIFL Finance provide an early demonstration of the model. The next phases, particularly secondary-market trading and potential retail participation, will provide a broader test of the infrastructure.
For participants in the NCD and corporate bond ecosystem, the development is worth monitoring because it concerns the future infrastructure through which debt securities may be issued, settled and serviced.
At the same time, tokenisation should be viewed objectively. It does not eliminate the risks associated with corporate bonds, does not guarantee returns and does not replace the need for investors to review the relevant offer documents and risk factors.
The long-term importance of Demat 2.0 will ultimately depend on how effectively the technology works within India’s existing regulatory framework and whether it delivers measurable improvements while maintaining market integrity and investor protection.
Disclaimer
Investments in debt securities are subject to risks. Read all the offer related documents carefully. This article is for general informational and educational purposes only and should not be construed as investment advice, an offer, solicitation or recommendation to invest in any security. Investors should independently evaluate the relevant offer documents, risk factors and applicable disclosures before making any investment decision. The information relating to Demat 2.0 is based on publicly available information and may be subject to regulatory or operational changes.